Turn your rental property into a long-term investment with financing designed for real estate investors. Qualify primarily based on the property’s rental income, without relying on personal income or tax returns.
Whether you’re purchasing a new rental, refinancing after a renovation, or expanding your portfolio, our Rental Loan Program offers competitive rates and flexible options for both long-term and short-term rental properties.
Park Place Finance DSCR Loans are designed for various Rental Properties to meet your Investment Real Estate Needs.
You’ll love the ease of closing with Park Place Finance, because of our common sense underwriting. No Tax Returns, No Income Verification, and Primarily Credit, Property Details and Debt Ratio to Qualify! To speed up the process, here are the main items you’ll need to gather:

Close within 5-7 business days

Competitive Rates From 8.99%

Nationally Trusted within 48 states
Whether you’re financing your first investment property or taking on a multimillion-dollar luxury project, Park Place Finance has financing solutions designed to meet you at every stage. We work with first-time investors, experienced operators, builders, and developers nationwide, providing flexible private capital for projects of all sizes. Our goal is to provide the financing, speed, and support investors need to complete their objectives and position their investments for a successful return.
Debt Service Coverage Ratio. This is simply = your total payment / your total rents. If this number is 1.0 or greater, than your rents are higher than your total payment. The higher that is, the better your rate generally is.
The ratio is calculated by dividing the property income (rental income) from the property PITIA (principal + interest + taxes + property insurance+ homeowners association dues). The resulting ratio lets the lender know how much income is available to pay the mortgage. A ratio of 1.0x means that the property that the revenue from rental income AND expenses is equal. A DSCR above 1 means the property is positively cash-flowing. Conversely, a DSCR of less than one means that the expenses exceed the rental revenue and the property has a negative cash-flow.
There’s many reasons clients prefer DSCR loans vs. Conventional financing. First, DSCR loans do not take into account your other debts beyond the PITI payment of your loan. So, if you are self employed and report very little income, using a DSCR loan may be the best option.
Secondly, a DSCR loan does not report to credit, and therefore may not affect your future ability to qualify for additional properties.
Another benefit is that a DSCR loan allows you to vest in an LLC , whereas FNMA does not allow that on traditional financing.
The top 3 factors that affect the DSCR rate include the actual Debt Service Coverage Ratio (DSCR), Loan-to-Value, and your FICO (credit score). The higher the DSCR is on a property, the lender is able to forecast a lower risk for lending the capital since the property may be positively cash-flowing and the investor is able to pay the monthly loan payments. Loan-to-Value, or LTV, refers to the loan amount as it relates to the actual value of the property. Typically, DSCR loans will never exceed 80% LTV. That means that the borrower needs to bring about 20% +closing costs as a down payment for the loan. The lower the LTV, the less risk for the lender, hence a better rate. Finally, your credit score is still a factor when determining the rate. Lenders use the score and it affects the final rate for your DSCR loan.
Rates vary daily, but typically DSCR loan rates can be lower than conventional, depending on leverage and credit. However, DSCR loans are much easier to qualify for given the fact they do not take into account your personal income.

Rental Loan Program
Loan Amount: $897,500
LTV: 68%
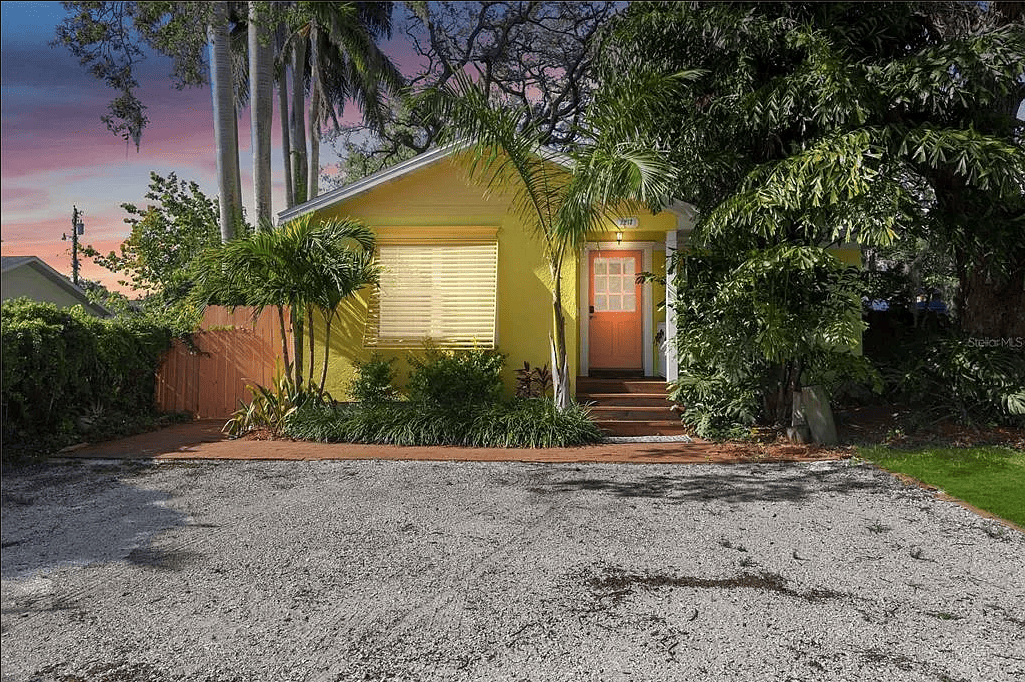
Rental Loan Program
Loan Amount: $339,750
LTV: 75%
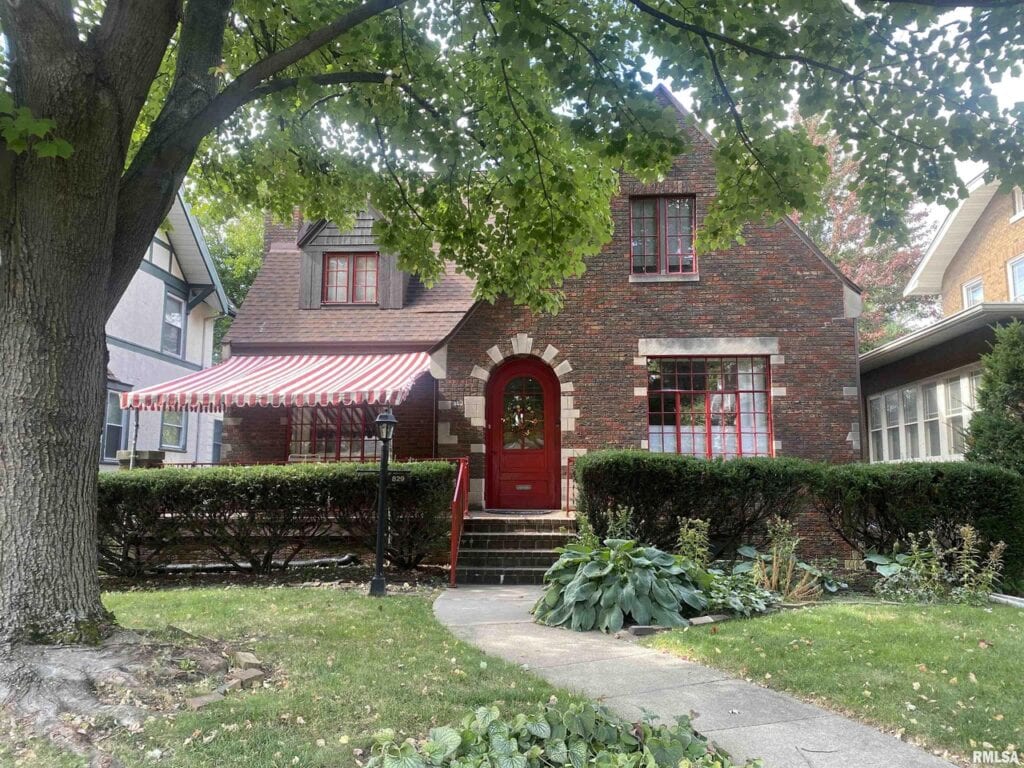
Rental Loan Program
Loan Amount: $114,750
LTV: 75%
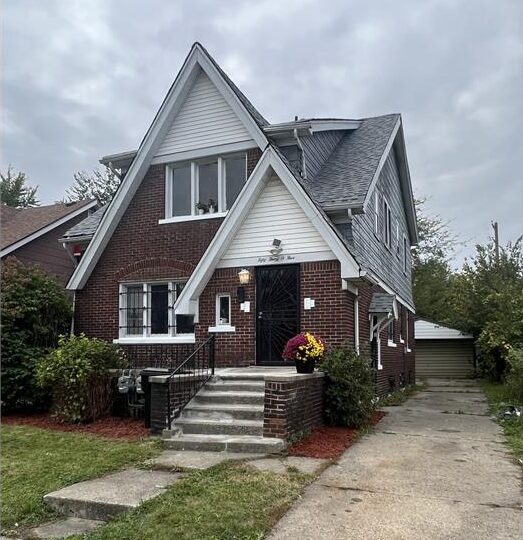
Rental Loan Program
Loan Amount: $118,125
LTV: 75%
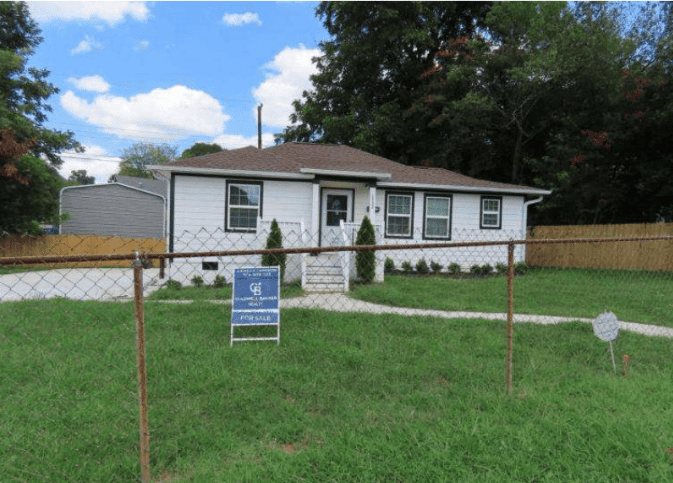
Rental Loan Program
Loan Amount: $100,021.50
LTV: 35.85%
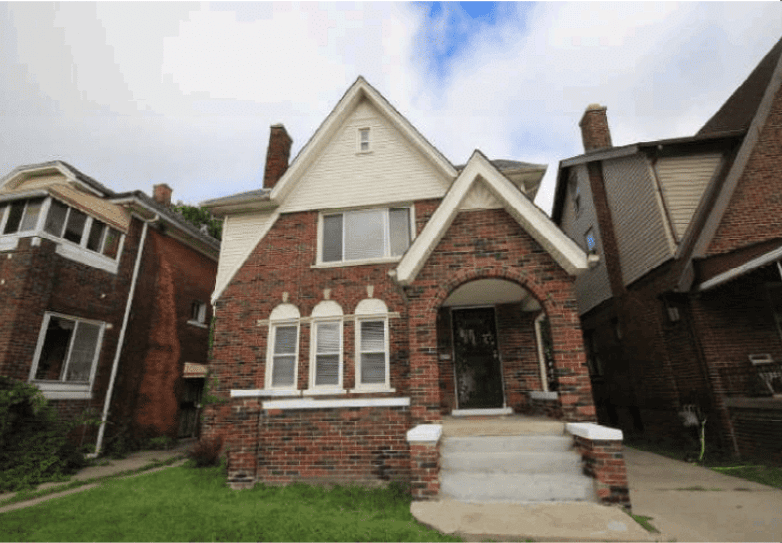
Rental Loan Program
Loan Amount: $116,250
LTV: 75%